Asset Protection
Insurance, legal structures, estate planning, and strategies for protecting personal and business wealth.
You have probably tried this before. An app, a spreadsheet, a notebook from the drugstore. It worked for a week or two, then a grocery run went over, or a friend’s wedding showed up out of nowhere, and the whole thing quietly stopped. You are not failing at budgeting. Your last budget was not built to survive an average month.
This guide shows you how to calculate the income your budget should actually use, how to pick a method that fits your life instead of someone else’s, and how to build a working budget using real numbers. You will also get a specific plan for the exact moment you overspend a category, since that is where most budgets die.
Most budgets fail because the plan was unrealistic, not because the person lacked discipline. A budget that assumes you will suddenly stop spending on things you have always spent on is not a plan. It is a wish list, and wish lists do not survive a real paycheck.
More Americans are trying anyway. According to YouGov’s 2026 survey on budgeting trends, 53 percent of Americans had set a budget for 2026, up from 46 percent in 2025. That increase matters. Budgeting is becoming a normal financial habit, not a niche one reserved for people who are bad with money.
A budget that “actually works” accounts for all three. It starts from what you really spend, builds in a buffer, and gets reviewed on a schedule instead of only when something goes wrong.
“Every dollar figure in this guide is checked against the original BLS, Federal Reserve, or New York Fed release before it goes out. That is the standard we hold every budgeting article to.” Tanner Medina, Business Investor
Your budget should run on take-home pay, the amount that actually lands in your bank account after taxes and payroll deductions, not your gross salary. Gross income includes money you will never see, like taxes and retirement contributions. Building a budget around that number sets you up to overspend from day one.
If you get a steady paycheck, this step takes five minutes. Add up your net deposits for one typical month. If you have irregular income from freelancing, gig work, tips, or commission, use a more conservative approach:
This approach protects against building a budget around a good month that does not repeat. The Consumer Financial Protection Bureau’s free Your Money, Your Goals toolkit includes income and spending trackers built for exactly this kind of income variability, at no cost.
The right budgeting method is the one you will still use in month three, not the one that sounds the most disciplined. Four methods cover most people: 50/30/20, zero-based, the envelope system, and pay yourself first. Each one solves a different problem, so the fit depends on your income pattern and what tends to derail you.
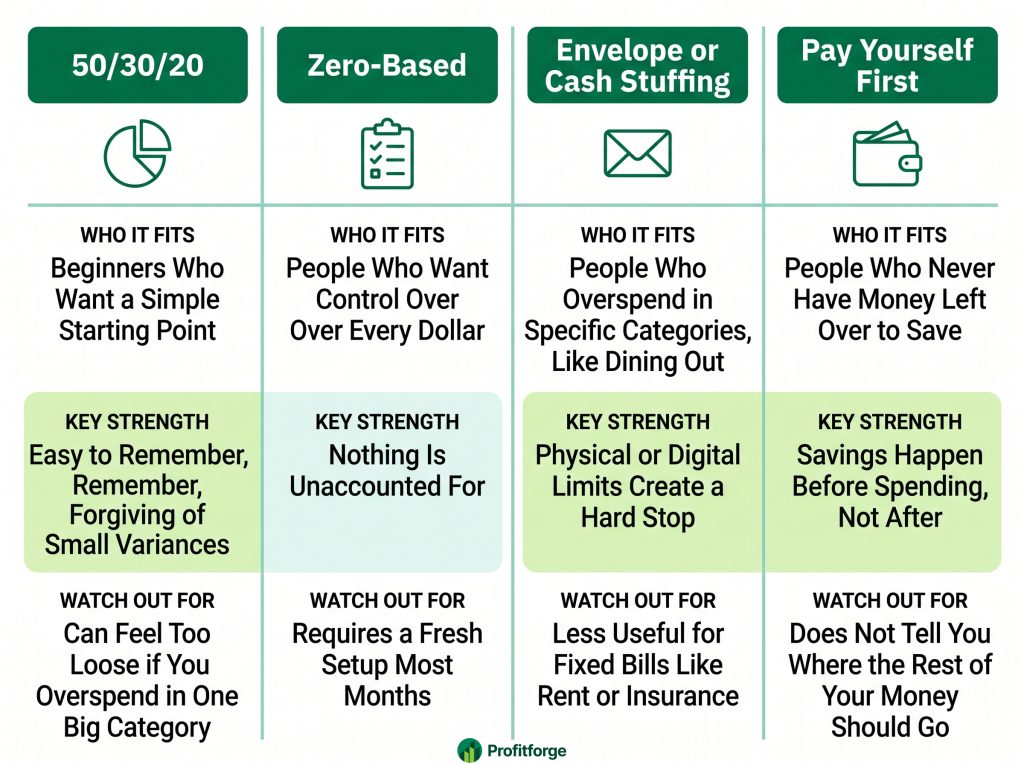
| Method | Who It Fits | Key Strength | Watch Out For |
|---|---|---|---|
| 50/30/20 | Beginners who want a simple starting point | Easy to remember, forgiving of small variances | Can feel too loose if you overspend in one big category |
| Zero-Based | People who want control over every dollar | Nothing is unaccounted for | Requires a fresh setup most months |
| Envelope or Cash Stuffing | People who overspend in specific categories, like dining out | Physical or digital limits create a hard stop | Less useful for fixed bills like rent or insurance |
| Pay Yourself First | People who never have money left over to save | Savings happen before spending, not after | Does not tell you where the rest of your money should go |
The 50/30/20 rule splits after-tax income into 50 percent needs, 30 percent wants, and 20 percent savings and debt repayment. It comes from a real, citable source. Then-Harvard Law professor and current U.S. Senator Elizabeth Warren and her daughter Amelia Warren Tyagi popularized it in their 2005 book, as detailed in Transamerica’s history of the 50/30/20 rule. It works well as a starting point because it gives you three buckets instead of twenty categories to track.
Zero-based budgeting goes further. Every dollar gets a job, whether that job is rent, groceries, debt, or fun money, until income minus expenses equals zero. It takes more setup time each month but leaves nothing unassigned, which appeals to people who feel anxious when they do not know exactly where their money went.
The envelope system works differently. You divide cash, physical or digital, into labeled categories like groceries or dining out, and spending in that category stops once the envelope is empty. Pay yourself first flips the order of operations entirely. Savings and debt payments move out of checking on payday, before any other spending happens, so whatever is left funds the rest of the month.
“I treat a personal budget the same way I treat a startup’s cash flow statement. If the categories do not match what actually happened last month, the plan is fiction, not a forecast.” Derick Do, Business Investor
The fastest way to see whether a method fits is to run your real income through it. Below is a worked example using $5,000 in monthly take-home pay, first under 50/30/20 and then under a full zero-based structure, so you can see how the same income produces two different plans.
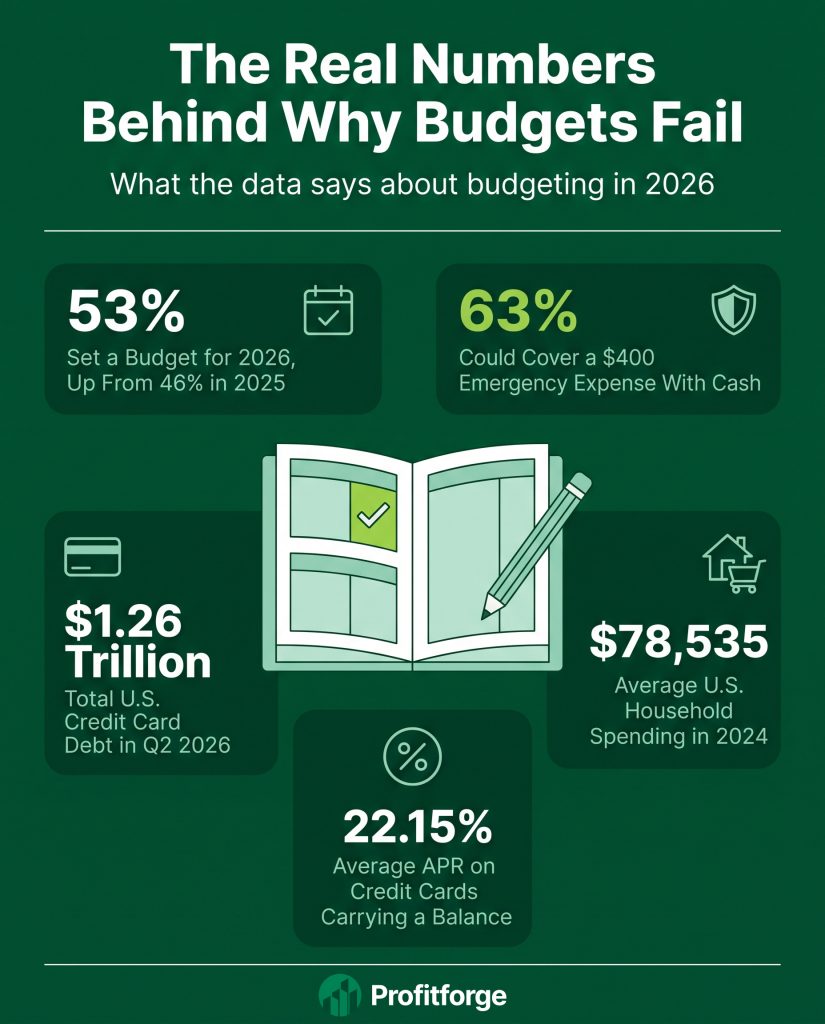
For context, the Bureau of Labor Statistics’ 2024 Consumer Expenditure Survey found that average annual household spending was $78,535 against average income before taxes of $104,207. Housing and transportation carry real weight in that total. BLS data on average household spending shows housing alone averaged $2,189 a month, or 33.4 percent of total spending, and transportation averaged $1,110 a month, or 17.0 percent. Together those two categories can fill most of a needs bucket, which is exactly why the needs percentage in 50/30/20 sits at 50 percent instead of lower.
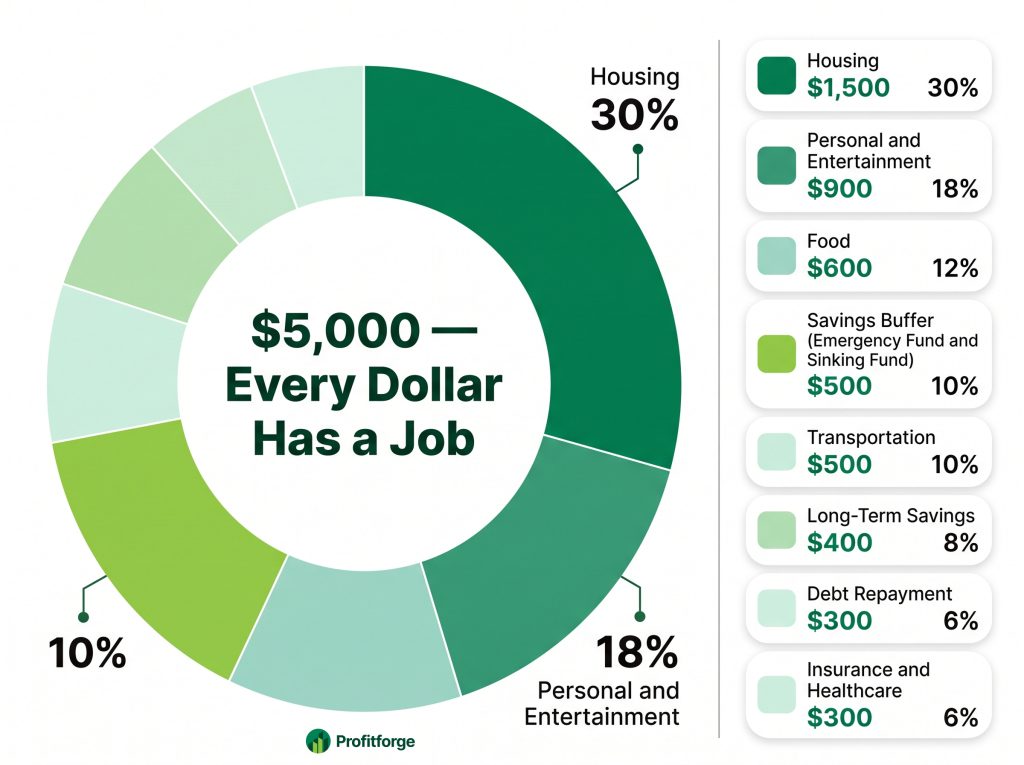
| Category | Monthly Amount |
|---|---|
| Housing | $1,500 |
| Transportation | $500 |
| Food | $600 |
| Insurance and healthcare | $300 |
| Debt repayment | $300 |
| Savings buffer (emergency fund and sinking fund) | $500 |
| Personal and entertainment | $900 |
| Long-term savings | $400 |
| Total | $5,000 |
Every dollar of the $5,000 has a category. Nothing sits unassigned, and nothing gets spent by default. This version takes longer to build the first time, but it gives a clearer answer to where the money went than percentage buckets alone.
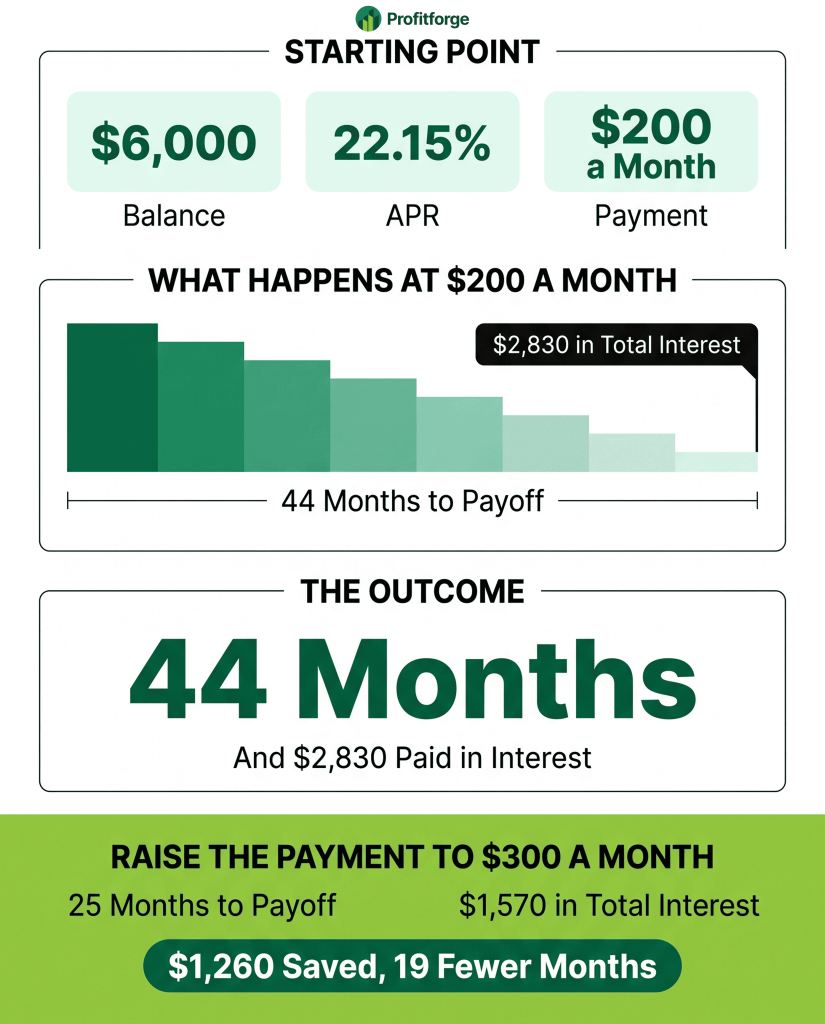
Paying more than the minimum on high-interest debt changes your payoff timeline more than most people expect. Total U.S. credit card debt reached $1.26 trillion in the second quarter of 2026, according to the New York Fed’s second quarter 2026 household debt report. LendingTree’s analysis of Federal Reserve interest rate data put the average APR on cards carrying a balance at 22.15 percent that same quarter.
Here is what that rate does to a real balance. A $6,000 balance at 22.15 percent APR, paid at $200 a month, clears in about 44 months and costs roughly $2,830 in interest. Raise the payment to $300 a month and the same balance clears in about 25 months, costing roughly $1,570 in interest. That is about $1,260 saved and 19 fewer months of payments for an extra $100 a month. This is why a debt repayment line inside your budget, even a modest one, is worth more than it looks on paper. These figures are illustrative and will shift with your actual balance, rate, and any new charges.
If you want to run your own numbers instead of the example above, a Profitforge budget calculator lets you plug in your take-home pay and see the 50/30/20 and zero-based versions side by side.
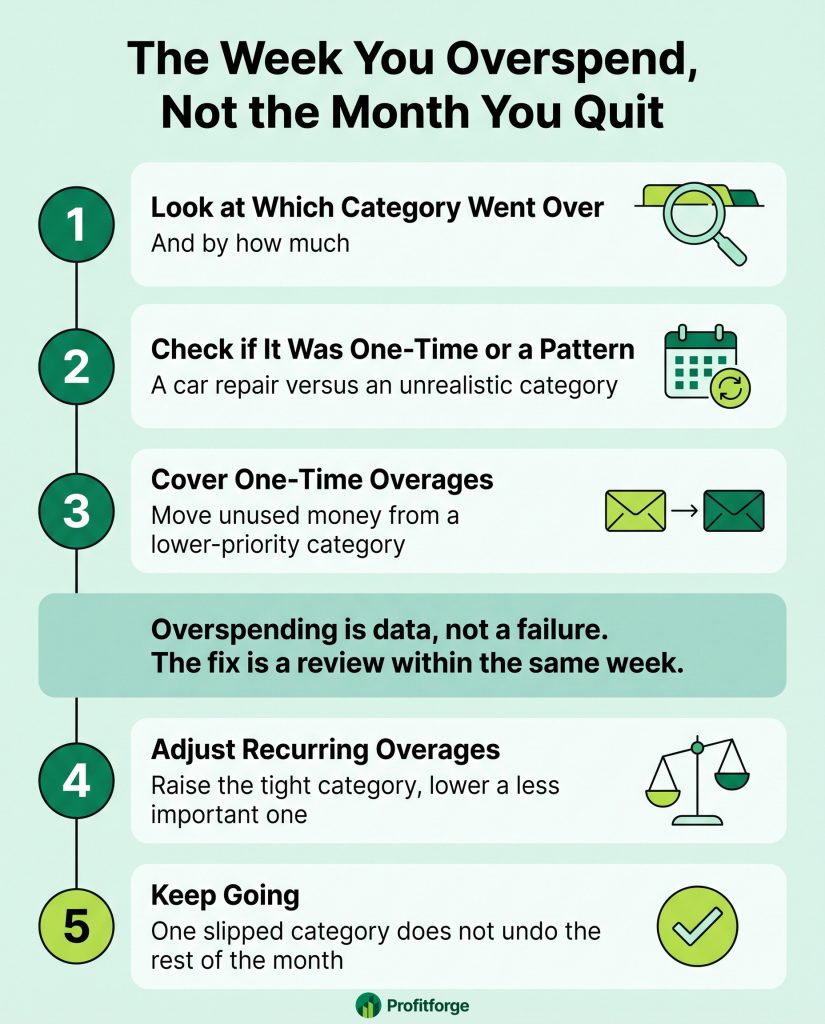
Overspending a category is not a sign your budget failed. It is data, and the fix is a review within the same week, not a full restart. Most budgets that get abandoned die at exactly this moment, when one bad week feels like proof the whole plan does not work.
“The clients who stick with a budget are not the ones who never overspend. They are the ones who look at the number two days later instead of two months later.” Emily Brooks, Financial Coach & Money Management Expert
Kirk Kinder, director of financial planning at Bastion Fiduciary, told Yahoo Finance that closely tracking spending helps people find inefficient or unnecessary spending, like unused subscriptions and bank fees, and that the habit works whether someone is trying to save more or get out of debt. That review habit, not a perfect first month, is what makes a budget durable.
Your emergency fund belongs inside your budget as its own line item, not as a leftover goal you get to once everything else is covered. Without that buffer, the first surprise expense forces you to pull from another category or reach for a credit card, which undoes the plan you just built.
The Federal Reserve’s 2025 Report on the Economic Well-Being of U.S. Households found that only 63 percent of adults could cover a $400 emergency expense using cash or its equivalent, a share unchanged since 2022. Vanguard’s 2025 research on emergency savings and financial well-being found that emergency savings was the strongest predictor of financial well-being among more than 12,400 investors surveyed, and cited separate Federal Reserve data showing 36 percent of Americans would struggle to cover that same $400 expense.
Start with a specific, achievable target rather than an open-ended goal.
Your tracking method needs to match your actual habits, not the method you think you should prefer. A budget you never look at is not a budget. The most common reason people stop tracking is that they picked a tool that fought against how they naturally manage money.
Low-tech tracking is still the norm, not a lesser option. Debt.com’s 2026 Budgeting Survey found that pen and paper remained the most common budgeting method in 2026 at 37 percent, followed by spreadsheets at 27 percent and mobile apps at 22 percent. The same survey found that 44 percent of respondents said their whole household works together to stay on budget, which suggests tracking sticks better as a shared habit than a solo chore.
“Most budgeting apps fail people the same way. They automate categorization but never prompt a weekly look. Pick a tool based on whether it nudges you to check in, not on how many features it has.” Kevin Douglas, Technology & Finance Tools Analyst
Bryan Gum of Lighthouse Planning recommends a short quarterly check-in built around three questions, reported in the same Yahoo Finance piece cited above: what did your money make easier this quarter, what did it make harder, and would you feel good about where it is going a year from now. That fifteen-minute habit, repeated four times a year, does more for a budget’s survival than any single tool choice.
If keeping up with categories by hand feels like too much to manage alone, a free Profitforge budget template gives you a pre-built version of the categories used in the examples above, ready to fill in with your own numbers.
Pick one method from the comparison table, run it against your real take-home income using the worked examples above, and set a calendar reminder to review it in two weeks, not two months. That short first review is where most budgets either find their footing or reveal which category needs adjusting.
As Juan Carlos Medina, CFP, put it in a Forbes contributor piece on why budgets fail, a budget works best when it reflects who you are and what you actually value, and readers who need more structure should not hesitate to bring in a qualified financial planner or coach. Start small, expect to adjust, and treat the first few months as a draft rather than a final version.
The 50/30/20 rule works well for most beginners because it uses only three categories and is forgiving of small variances. Zero-based budgeting gives tighter control once the basics feel comfortable.
Most financial educators suggest building a $500 to $1,000 starter emergency fund first, then splitting extra money between debt repayment and continuing to grow that fund. The right split depends on interest rates and income stability, so a household carrying 22 percent APR debt will usually lean harder toward payoff than one with a low fixed-rate loan.
Base the budget on the lowest month from the past three to six months, not the average. Treat any income above that baseline as a bonus to move directly into savings or debt payoff instead of building it into regular spending categories.
Neither is inherently better. An app works well for automatic categorization and frequent phone check-ins. A spreadsheet works well for full control and no subscription cost. Debt.com’s 2026 survey found pen and paper is still the single most common method, so the right choice is whichever one actually gets used.
Review the category within the same week. If it was a one-time expense, cover it by shifting unused money from another category. If it happens most months, raise that category’s budget next month and lower a less important one to balance it out.